Business
Smart Investment Strategies for Building Long-Term Financial Security

Building long-term financial security requires more than simply putting money aside and hoping that it grows over time. Investors need to understand their financial objectives, evaluate potential risks, select appropriate investments, and review their strategies as circumstances change. Financial markets can move through periods of growth, uncertainty, and decline, making discipline an important part of successful investing. A well-structured strategy considers both current financial needs and future goals while allowing enough flexibility to adapt when circumstances change. An investment manager can provide professional guidance throughout this process by helping investors evaluate opportunities, understand portfolio risks, organize investments, and maintain a strategy that is connected to their broader financial objectives rather than short-term market movements.
- Understanding the Basics of Investment Management
- Defining Clear Financial Goals
- Evaluating Risk Before Investing
- The Importance of Diversification
- Developing a Long-Term Strategy
- Understanding Asset Allocation
- Monitoring Investment Performance
- Managing Market Volatility
- Considering Investment Costs
- Planning Around Investment Time Horizons
- Creating a Strategy for Investment Income
- Considering Tax Implications
- Preparing for Unexpected Financial Changes
- Maintaining Financial Discipline
- Reviewing and Rebalancing a Portfolio
- Adapting to Changing Financial Goals
- The Role of Professional Guidance
- Making Informed Investment Decisions
- Building Long-Term Financial Security
- Final Thoughts
Understanding the Basics of Investment Management
Investment management is the process of managing financial assets with the purpose of supporting specific financial goals. It can involve selecting investments, determining how assets should be allocated, monitoring portfolio performance, managing risk, and making adjustments when circumstances change. The process is different for every investor because financial goals, income levels, investment horizons, and tolerance for market fluctuations vary considerably. An investment manager can review these factors before developing a portfolio strategy designed around an individual’s circumstances. This structured approach can make financial decisions more organized and may help investors avoid making significant changes based only on temporary market movements or emotional reactions to financial news.
Defining Clear Financial Goals
A strong investment strategy begins with clearly defined goals because the purpose of investing influences how money should be managed. Some individuals may be focused on building long-term wealth, while others may want to generate future income, prepare for retirement, fund education, purchase assets, or preserve capital for their families. Each objective can require a different combination of investments, risk levels, and time horizons. An investment manager can help turn general financial ambitions into specific objectives that can be monitored over time. Establishing clear goals also provides a useful standard for evaluating portfolio performance because investors can consider whether their strategy is helping them move toward their intended financial outcomes rather than focusing exclusively on short-term gains or losses.
Evaluating Risk Before Investing
Risk is an unavoidable part of investing, and understanding it is essential before committing money to financial markets. Different investments can experience different levels of price volatility, and the possibility of higher returns may come with greater potential losses. Investors should consider not only how much financial risk they are comfortable taking but also how much risk their financial situation can reasonably support. An investment manager can assess factors such as income, existing assets, financial obligations, investment horizon, liquidity requirements, and tolerance for market fluctuations. This information can help determine an appropriate balance between growth opportunities and portfolio stability. Understanding risk in advance can also help investors remain disciplined during periods when markets become unpredictable.
The Importance of Diversification
Diversification is one of the fundamental principles of portfolio management because concentrating investments in a limited number of assets can increase exposure to specific risks. A diversified portfolio may include different asset classes, industries, companies, geographical markets, or investment strategies depending on the investor’s objectives. The purpose of diversification is not to guarantee profits or completely eliminate losses, but to reduce the potential impact of poor performance in any single area. An investment manager can review how individual holdings interact with the broader portfolio and determine whether the overall allocation is sufficiently diversified. Regular reviews are important because changes in market values can cause a portfolio to become more concentrated than originally intended.
Developing a Long-Term Strategy
Long-term investing requires patience because financial markets do not move upward consistently. Investors may experience strong periods of growth followed by corrections, recessions, uncertainty, or extended periods of volatility. Reacting to every short-term market movement can cause investors to abandon carefully considered strategies at unfavorable times. A long-term approach focuses on the objectives that originally led to the investment rather than attempting to predict every market movement. An investment manager can help maintain this perspective by reviewing market developments within the context of the investor’s overall financial plan. Having a defined strategy can make it easier to evaluate whether changes are genuinely necessary or simply reactions to temporary market conditions.
Understanding Asset Allocation
Asset allocation refers to how an investment portfolio is distributed among different categories of assets. The appropriate allocation depends on factors such as financial goals, time horizon, risk tolerance, income requirements, and liquidity needs. Someone investing for a distant financial objective may have different allocation requirements from someone who expects to use the money within a few years. An investment manager can evaluate these factors and determine how the portfolio might be structured to reflect the investor’s circumstances. Asset allocation should also be reviewed periodically because market performance, personal circumstances, and financial priorities can change. Maintaining an appropriate allocation can help ensure that the portfolio continues to reflect the investor’s intended level of risk.
Monitoring Investment Performance
Investing does not end once a portfolio has been established. Regular monitoring is important because financial markets change and an investor’s circumstances can evolve over time. Portfolio performance can be evaluated by looking at returns, risk levels, diversification, investment costs, and progress toward specific financial goals. Simply seeing that an account balance has increased or decreased does not provide a complete picture of whether a strategy is working appropriately. An investment manager can review performance against relevant benchmarks and consider whether portfolio changes are necessary. Regular monitoring can also identify situations where investments have become overly concentrated or where the portfolio no longer matches the investor’s original objectives.
Managing Market Volatility
Market volatility can create emotional challenges for investors, particularly when financial markets experience rapid declines. Seeing portfolio values fall can lead individuals to question their investment strategies or consider selling assets unexpectedly. However, short-term market movements do not necessarily change the long-term fundamentals behind an investment plan. Investors should consider their time horizon and financial objectives before making significant changes during periods of uncertainty. An investment manager can provide perspective by explaining potential risks, reviewing the portfolio’s structure, and considering whether the current allocation remains appropriate. A disciplined strategy can help investors distinguish between temporary market fluctuations and circumstances that may genuinely require a change in their financial plan.
Considering Investment Costs
Investment costs can have a meaningful effect on long-term financial outcomes, especially when fees continue to accumulate over many years. Depending on the investments and services involved, costs may include management fees, transaction expenses, fund expenses, advisory charges, or other account-related costs. Investors should understand what they are paying and what services those costs cover before committing to a particular strategy. An investment manager should provide clear information about applicable fees and explain how they relate to portfolio management and other services. Evaluating costs alongside investment objectives, risk management, service quality, and portfolio strategy can help investors make more informed decisions about how their financial assets are managed.
Planning Around Investment Time Horizons
Time horizon is another important consideration because the amount of time available before money is needed can influence the appropriate level of investment risk. Long-term investments may have more opportunity to recover from temporary market declines, while assets needed in the near future may require greater attention to liquidity and stability. Investors should therefore separate short-term financial needs from long-term investment objectives whenever possible. An investment manager can help categorize financial resources according to when they are likely to be needed and consider how each portion of the portfolio should be managed. This approach can help reduce the risk of relying on volatile investments for expenses that are expected to occur in the near future.
Creating a Strategy for Investment Income
Some investors are primarily interested in growing their assets, while others need their investments to generate regular income. Income may be particularly important for people approaching or living in retirement, but it can also be relevant to individuals seeking additional cash flow from their assets. Creating an income-focused strategy requires consideration of portfolio composition, withdrawal requirements, market conditions, taxes, and the sustainability of distributions. An investment manager can help evaluate different approaches while considering both present income needs and the long-term preservation of capital. A balanced strategy should recognize that taking excessive withdrawals may reduce the amount of money available for future needs, particularly during periods of weak investment performance.
Considering Tax Implications
Investment decisions can have tax consequences, and these should be considered as part of broader financial planning. Different investments, account types, transactions, and income sources may receive different tax treatment depending on applicable rules and individual circumstances. Investors should understand how potential taxes may affect their overall financial results rather than evaluating investments only by their headline returns. An investment manager can work with appropriate tax professionals when necessary to ensure that investment decisions are considered within the broader financial picture. Tax considerations do not necessarily determine every investment decision, but understanding them can help investors evaluate the potential benefits and costs associated with different strategies.
Preparing for Unexpected Financial Changes
Financial plans should account for the possibility that circumstances may change unexpectedly. Investors may experience changes in employment, income, family responsibilities, business interests, major expenses, or financial priorities. Market conditions can also develop differently from expectations, which makes flexibility important. An investment manager can help review how a portfolio might respond to different financial scenarios and identify potential areas of vulnerability. Scenario planning can involve considering periods of lower investment returns, unexpected expenses, changing income needs, or shifts in financial objectives. Although nobody can predict every future event, preparing for a range of possibilities can make an investment strategy more adaptable and resilient.
Maintaining Financial Discipline
Successful investing often requires discipline because financial markets can create strong emotional reactions. During periods of rapid growth, investors may feel pressure to take greater risks, while market declines can create fear and uncertainty. Making major financial decisions based solely on emotions can cause an investor’s strategy to change repeatedly without a clear connection to long-term goals. An investment manager can help provide structure by reviewing decisions against established objectives, risk limits, and portfolio guidelines. Maintaining a consistent process can make it easier to evaluate opportunities objectively and avoid unnecessary changes that may weaken an otherwise carefully designed investment strategy.
Reviewing and Rebalancing a Portfolio
Over time, investment performance can cause a portfolio’s original asset allocation to change. For example, an asset that performs particularly well may become a much larger percentage of the portfolio than initially intended. This can increase exposure to a particular investment or asset category and alter the overall level of risk. Portfolio reviews can identify these changes and determine whether rebalancing may be appropriate. An investment manager can evaluate the current allocation against the intended strategy and consider whether adjustments are necessary. Rebalancing should be based on the investor’s objectives and circumstances rather than performed simply because markets have moved in a particular direction.
Adapting to Changing Financial Goals
Financial priorities can change throughout a person’s life. An investor may initially focus on accumulating wealth but later prioritize retirement income, capital preservation, education funding, charitable giving, or estate planning. Major life events can also influence financial objectives and the amount of risk an individual is willing to accept. An investment manager can help review the portfolio when these changes occur and determine whether the existing strategy remains suitable. Regular communication is important because a portfolio designed around goals from many years ago may not remain appropriate if the investor’s financial circumstances or priorities have changed significantly.
The Role of Professional Guidance
Managing investments can become increasingly complicated as portfolios grow and financial circumstances become more diverse. Investors may need to coordinate multiple accounts, asset classes, income sources, tax considerations, insurance needs, and long-term financial goals. Professional guidance can provide an organized framework for bringing these elements together. An investment manager can assist with portfolio construction, investment research, risk assessment, performance monitoring, and ongoing strategy reviews. When evaluating professional services, investors should consider qualifications, fees, communication practices, investment philosophy, transparency, and the range of services provided. Clear communication is especially important because investors should understand how their assets are being managed and why particular strategies are being considered.
Making Informed Investment Decisions
Informed investment decisions begin with understanding the purpose of the money, the time available for investment, the level of risk that can reasonably be accepted, and the potential consequences of different choices. Investors should avoid relying solely on market headlines or short-term predictions when making significant financial decisions. Research, diversification, disciplined portfolio management, and regular reviews can provide a more structured foundation for long-term investing. An investment manager can help organize this information and explain how different investment choices may affect the broader portfolio. The objective is not simply to pursue the highest possible return but to develop a strategy that balances growth, risk, liquidity, and long-term financial objectives.
Building Long-Term Financial Security
Long-term financial security is usually developed through consistent decisions rather than one major investment choice. Saving regularly, investing according to clearly defined objectives, managing risk, reviewing portfolio performance, and adapting to changing circumstances can all contribute to a more organized financial strategy. Investors should recognize that market returns are uncertain and that no strategy can eliminate financial risk completely. However, a structured approach can make it easier to identify potential challenges and respond thoughtfully when circumstances change. An investment manager can support this process by providing ongoing oversight and helping investors maintain a strategy that remains connected to their financial goals. With realistic expectations and regular reviews, investors can create a financial framework designed to support their priorities over the long term.
Final Thoughts
Investment management is an ongoing process that requires planning, discipline, research, risk awareness, and regular evaluation. A strong strategy should reflect an individual’s financial objectives, investment horizon, liquidity needs, and ability to tolerate market fluctuations. Diversification can help manage concentration risk, while regular portfolio reviews can ensure that investments remain aligned with changing circumstances. Professional guidance may also provide valuable structure for investors who want assistance with portfolio decisions, financial organization, and long-term strategy development. An investment manager can contribute to this process by helping evaluate investment opportunities, monitor portfolios, manage risk, and adjust strategies when appropriate. Ultimately, thoughtful investing is less about reacting to every market movement and more about maintaining a disciplined approach that supports clearly defined financial goals over time.

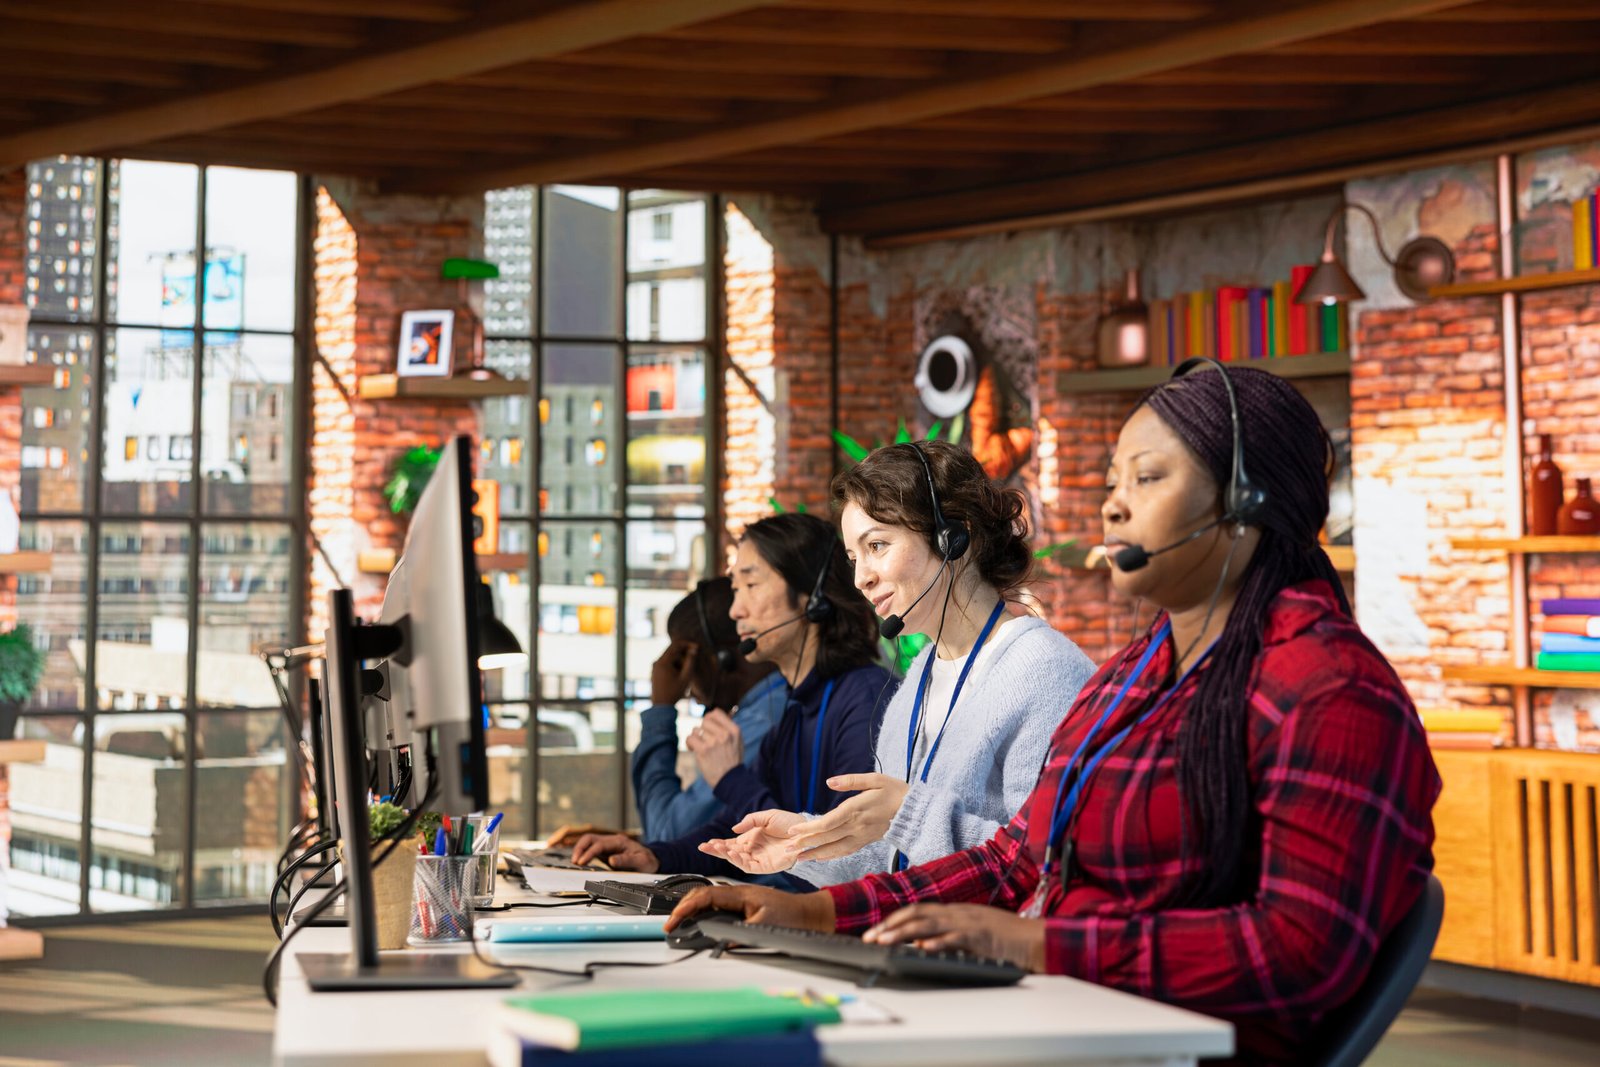
Customer support teams handle high call volumes by combining smart forecasting, flexible staffing, clear call routing, self-service tools, and queue management. Any support team can be overwhelmed with an influx of phone calls. Customers face long hold times. Support agents deal with rising stress.
- Forecast Call Demand to Prepare for Peak Periods
- Adjust Staffing and Agent Schedules to Match Demand
- Use Automatic Call Distribution to Route Calls Efficiently
- Offer Self-Service Options to Resolve Routine Inquiries
- Reduce Queue Pressure With Callbacks and Virtual Hold
- Distribute Support Across Phone, Chat, Email, and Messaging
- Equip Agents With Training, Knowledge Bases, and Customer Data
- Track Call Volume and Service Metrics in Real Time.
- Review Call Spikes to Improve Future Support Operations
- Conclusion
By pairing excellent processes with practical support tools, you can safeguard customer service, while keeping wait times in check. Here’s how today’s contact centers do just that day after day.
Forecast Call Demand to Prepare for Peak Periods
All smart customer service leaders analyze the history of calls to identify trends. Busy periods often follow a predictable schedule. For instance, a retailer might receive more customer inquiries to their business during a holiday flash sale. Call numbers are also increased by product releases and periodic billing cycles. Leaders analyze this past data to make informed decisions about staff schedules.
Good planning helps your team anticipate customer needs before the phone lines fill up. However, there are times when things go awry. Any company can be caught off guard by sudden outages or delivery delays. Historical data can help you prepare for normal increases, but flexibility is required in the event of sudden shifts in customer needs.
Adjust Staffing and Agent Schedules to Match Demand
Workforce management helps a customer service team put the right people in the right places. Managers schedule shifts to avoid the rush of callers. They vary their lunch breaks and make flexible working times for support personnel. A smart manager also cross-trains the service teams so that they can answer other questions.
The flexibility safeguards operational efficiency against a surge of calls. It also helps to avoid employee burnout. When reps have to deal with a large number of calls in succession, service quality begins to diminish quickly. Sustainable scheduling ensures people are fresh and focused. That balance supports long-term business growth and equitable workloads for all support department staff on duty.
Use Automatic Call Distribution to Route Calls Efficiently
An automatic call distribution system sorts incoming calls and sends them to the right desks. This setup uses skills-based routing. This means the caller can speak with an agent who knows the topic they’re calling about. A basic interactive voice response menu gathers basic details from the caller. This is time-saving for the customer.
If a customer has an unpaid invoice, it is sent to billing; if a product is broken, it is sent directly to technical assistance. IVR reduces the number of transfers between different agents. Facilitates fewer handoffs while resolving calls. Good routing does not eliminate complex problems; it is about getting each caller to the right person, immediately.
Offer Self-Service Options to Resolve Routine Inquiries
Many callers are uncomfortable with waiting for an agent. They like having quick self-service to complete routine tasks. Allow individuals to reset passwords, view order tracking, or order hours on their own. Customers can be assisted at any time via searchable knowledge bases, account portals, and automated phone menus. This customer-centric approach saves time for everyone involved.
But, your self-service content needs to remain correct. Even if the tips are dated, people still call. Ensure information is available on all of the help pages in a clear and up-to-date format. Make sure all articles stay up to date. Above all, when automated help is insufficient, leave a path for a human agent to get there.
Reduce Queue Pressure With Callbacks and Virtual Hold
If call queues run long, they can frustrate customers. Callers do not enjoy hearing their calls played on hold. You can improve this wait by offering virtual hold. Virtual hold keeps a caller’s spot in line without keeping their phone pressed to their ear. The system provides availability of expected wait times and an automatic callback feature.
This feature ensures that customers don’t get upset during peak periods. It also respects customers’ time. Keep in mind that there will be a need for agent capacity on a callback. Your team will have to deal with these outgoing rings as well as live queues. Reliable callback tracking helps ensure no customer is lost while maintaining strong relationships and helps manage high call volumes all day.
Distribute Support Across Phone, Chat, Email, and Messaging
Depending on the immediate need, customers utilize different service channels. A strong customer service department offers phone, email, live chat, and text messaging. Live chat works great for quick questions. Email is used for less urgent requests and file attachments. Other channels free up phone lines for emergency calls.
An omnichannel platform consolidates all customer support tickets and contact history into a single platform. This way, no user has to repeat their story on other channels. This uniformity ensures a positive customer experience and improves the overall quality of the service provided. Providing customers with a number of choices ensures better customer service without losing customers to phone service.
Equip Agents With Training, Knowledge Bases, and Customer Data
Agents work best when they’re equipped with the proper tools and facts. A centralized database displays past orders and past notes for each individual customer contact. Reps can view past customer concerns right away. They don’t have to guess. Agents receive regular training in order to develop their soft skills and product knowledge.
If reps are knowledgeable about products, they provide excellent customer service on the initial call. This will avoid further follow-up calls from the same person later. Speed matters, but an accurate fix matters more. Solid preparation turns tense moments into helpful conversations that solve real problems for the caller.
Track Call Volume and Service Metrics in Real Time.
They monitor activity on the lines on live dashboards in their support software. They monitor activity metrics of the center such as average handle time, abandonment rates, queue lengths, etc. These numbers act as key performance indicators for overall team health. Managers change schedules or switch staff from email to phone lines when they experience an increase in abandonment. This helps to maintain a steady flow of tickets along the floor.
Leaders also monitor customer satisfaction metrics to guarantee that customers are getting quality answers. Fast responses mean nothing if the caller leaves unhappy. By monitoring the speed as well as satisfaction of customers, managers have a balanced picture of how the center is coping with incoming pressure in real time.
Review Call Spikes to Improve Future Support Operations
After the rush ends, your customer service team must study the numbers. Look at call reasons, peak hours, and abandoned connections. Review customer feedback to discover what went wrong. When people provide feedback, they offer valuable insights into confusing policies or broken products. Fixing these root problems protects your brand image. It also builds customer loyalty and aids long-term customer retention.
Use this data to train agents on complex tasks and create effective solutions for common complaints. Make sure explanations help customers understand policies easily. Help new customers navigate your service without frustration. This post-rush review turns a noisy call center into an engine for customer success. Excellent customer service comes from learning after every rush.
Conclusion
Managing heavy call queues requires thoughtful planning and clear action. When customer support teams blend smart forecasting, responsive staffing, practical routing, and self-service tools, they protect their team from burnout. Technology works best alongside trained agents and clear workflows.
Look at why callers reach out today. Eliminate avoidable friction at the source to protect your brand. Doing so drives business success and keeps satisfaction high. Audit your customer support workflows this week to prepare your team for the next busy season!

I used to think cyber security was mostly about having antivirus software,strong passwords,and maybe changing them every few months. It sounded kind of reasonable, you know,until I had to deal with a situation that made me view business security a little differently,not just the usual tech stuff.
- Why We Needed Cyber Security Services
- What I Noticed During the Process
- Actual Benefits of Cybersecurity Solutions
- Why Choose Cyber Security Consulting Services?
- Process
- Advantages for Modern Businesses
- Frequently Asked Questions
- What are cyber security services?
- Why is cyber security consulting important?
- What is a tabletop exercise in cyber security?
- Final Thoughts
It started with something small. One afternoon, a colleague mentioned that a strange login notification had appeared on one of our business accounts. Nothing had actually gone wrong, at least not that we could see. Still, everyone became a little more alert.
We started asking simple questions. Who had access? What information was stored there? What would happen if someone actually got into the system?
That was when I started looking seriously into cyber security services and realised how much more there was to it than I had originally assumed.
Why We Needed Cyber Security Services
The biggest issue wasn’t one particular computer. It was the way everything was connected.
We had emails, shared files, customer information, cloud applications and internal systems being used by different people every day. Some employees worked remotely, while others were in the office. It all worked smoothly, but that convenience also created potential gaps.
The things I became more concerned about were pretty straightforward:
- Protecting customer and business data
- Understanding who could access important systems
- Reducing the risk of phishing and account compromise
- Improving everyday IT security practices
- Having a plan if something actually went wrong
This was where cyber security consulting services started making sense to me. Instead of simply buying another security product, we needed someone to look at the bigger picture.
What I Noticed During the Process
One thing that surprised me was how much of security involved people rather than technology.
We sat together and talked through different situations. What if someone received a convincing phishing email? What if an employee accidentally shared sensitive information? What if a critical system suddenly became unavailable?
The room got surprisingly quiet during some of those conversations.
We also discussed a tabletop exercise cyber scenario, which basically meant walking through a simulated security incident without actually causing one. It was a useful reality check. People knew their individual jobs, but we hadn’t really considered how everyone would respond together.
That exercise exposed small gaps in communication that we probably wouldn’t have noticed otherwise.
Actual Benefits of Cybersecurity Solutions
The biggest benefit wasn’t feeling completely “hack-proof” — because realistically, no business can promise that.
Instead, we became more prepared.
Our approach to computer security services became more practical. We started paying closer attention to access controls, backups, employee awareness and incident response. Data protection stopped being something we only thought about when there was a problem.
For me, the main improvements were:
- Better awareness across the team
- Clearer responsibilities during an incident
- Stronger protection around important information
- More confidence in our everyday systems
- A more organised approach to business security solutions
Why Choose Cyber Security Consulting Services?
I think the biggest reason is perspective.
A business can have security software installed everywhere, and still kinda end up with weak processes. Cyber security consulting services can help spot those gaps, and get the connection right between technology, people and procedures, not just treating them as separate bits or stuff like that.
This becomes pretty vital for companies looking for cyber security services Australia-wide, where remote work, cloud platforms, and connected systems are basically everyday normal now, part of daily operations, even when nobody really says it out loud.
During our search, Vintaris Solutions Pty Ltd was one company that stood out to me because the conversation around security felt focused on the actual business rather than just selling another tool.
Process
The process wasn’t as complicated as I had imagined.
First, we kinda looked over the systems and the info that felt most important. Then we talked about what security practices were already there, plus access, and those possible risks. After that, we worked through a few “what if” incidents and thought about how the business would respond, if it ever actually happened.
The tabletop exercise was probably the most memorable part, because it made everything feel real, without really throwing actual systems into danger. It also, in a weirdly clear way, showed why good IT security services have to include planning and communication , not only technical protection.
Advantages for Modern Businesses
Good cybersecurity solutions can help modern businesses in a few practical ways. They can protect sensitive information, cut down disruption, and also make employees more aware of everyday dangers.
For any business searching for cyber security services Australia, the key thing , in my experience , is finding an approach that actually matches the organisation you have, not just copying someone else’s security setup and hoping it “fits”.
Frequently Asked Questions
What are cyber security services?
Cyber security services help businesses guard systems, networks, accounts, and data from cyber threats. They can cover security assessments, consulting, monitoring , risk management, plus incident response planning.
Why is cyber security consulting important?
Because it lets businesses see where security gaps might be sitting, and it shows how tech, people, and internal processes can work together to lower the risk overall.
What is a tabletop exercise in cyber security?
A tabletop exercise is basically a kind of made up discussion, where a team sort of walks through a pretend cyber incident. It helps see how communication actually moves, who is responsible , and if the response plans really click, sort of. Also it keeps things from turning into a real security incident, because that’s not the point.
Final Thoughts
When I look back, the biggest lesson was this , cybersecurity isn’t something you handle once and then forget. Technology changes, staff change , businesses grow, and new risks pop up. So security needs constant care, some ongoing attention, not just a quick fix.
What started as one strange login notification ended up shifting how I think about protecting data and business safety. I realised effective cyber security services aren’t only about blocking attacks. They’re also about knowing what happens next, who should move first, and how quickly the business can recover when something unexpected shows up.

Managing a business with limited financial resources presents a unique set of challenges that many entrepreneurs face, especially in the early stages of growth. The constraint of a tight budget forces business leaders to think strategically about every expense, prioritize ruthlessly, and find creative solutions that larger competitors may never consider. This reality, while demanding, often leads to stronger operational discipline and more sustainable business practices. Understanding how to allocate limited funds effectively can mean the difference between a business that survives and one that thrives.
Establish Clear Financial Priorities
The foundation of budget management begins with identifying what matters most to your business. Not all expenses carry equal weight, and distinguishing between essential costs and nice-to-have spending is critical. Your priority list should reflect what directly generates revenue or prevents your business from collapsing, so begin by mapping out your fixed costs, including rent, payroll, and insurance, before examining discretionary spending with a more critical eye. For example, if you run a consulting firm, investing in your own professional development and client communication tools becomes non-negotiable, while a fancy office space might be a luxury you defer until revenue grows. Once your fixed obligations are fully accounted for, you will be in a much clearer position to make informed decisions about where remaining funds can create the greatest impact.
Leverage Technology to Cut Operational Costs
Technology often represents an underutilized tool for budget-conscious business owners. Many affordable or free digital solutions can automate tasks that would otherwise require hiring additional staff or outsourcing. Cloud-based accounting software, project management platforms, and customer relationship management systems have democratized access to tools that were once available only to large corporations. By implementing these technologies thoughtfully, you can streamline workflows, reduce human error, and free up your team to focus on higher-value activities. For instance, automating invoice generation and payment reminders can significantly reduce the time your accounting team spends on administrative tasks, while scheduling tools can eliminate the back-and-forth communication that consumes productivity across many small businesses.
Negotiate with Vendors and Service Providers
Many business owners accept the first quote they receive, but vendors often have room to negotiate, particularly if you commit to a longer contract or agree to pay upfront. Building relationships with your suppliers creates opportunities for better pricing, flexible payment terms, or value-added services at no extra cost. Before renewing any service contract, take time to research competitors and gather alternative quotes so you can approach your current vendor with factual leverage. Armed with this information, you can ask them to match or beat competitor pricing, which often yields discounts without requiring you to switch providers. Small businesses can also explore vendor consolidation, reducing the number of suppliers they work with and potentially earning volume discounts in the process.
Implement Strategic Hiring Practices
Personnel expenses typically represent the largest portion of a business budget, making hiring decisions incredibly consequential. Rather than rushing to fill every open position with full-time employees, consider alternative staffing models that offer more flexibility. Contract workers, freelancers, and part-time employees allow you to scale your workforce based on actual business demands without committing to fixed payroll expenses. This approach also provides an opportunity to evaluate whether a role is truly necessary before making a long-term financial commitment. When you do hire full-time staff, invest in training and retention strategies that reduce turnover costs, as recruiting and onboarding new employees is far more expensive than retaining experienced team members.
Monitor Cash Flow Religiously
Understanding your cash flow patterns is essential for any business operating on a tight budget. Cash flow differs from profitability, and many profitable businesses fail because they run out of cash to cover immediate obligations. Create a detailed monthly cash flow projection that accounts for when money comes in and when it goes out, so you can anticipate shortfalls and adjust spending before you face a crisis. When aligning business cash flow strategy with longer-term financial planning, business owners rely on Dechtman Wealth to help ensure that short-term budget decisions support sustainable wealth-building goals. If you notice seasonal patterns in your revenue, use high-revenue periods to build reserves that carry you through slower months, and consider implementing payment policies that encourage faster customer payments, such as offering small discounts for early settlement.
Evaluate and Eliminate Wasteful Spending
Even well-intentioned businesses accumulate unnecessary expenses over time. Subscriptions renew automatically, memberships go unused, and services purchased for past projects continue to be paid for long after their relevance ends. Schedule a quarterly audit of all recurring expenses, asking for each vendor or service whether it actively supports your current business objectives and whether you would purchase it again if making the decision today. This practice often reveals subscriptions you forgot about, insurance coverage you no longer need, or vendor relationships that no longer provide value. Canceling even five unnecessary subscriptions at one hundred dollars each frees up six thousand dollars annually that can be redirected toward strategic investments with measurable returns.
Conclusion
Running a business on a budget requires discipline, intentionality, and a willingness to question every expense. By establishing clear financial priorities, leveraging technology efficiently, negotiating with vendors, implementing thoughtful hiring practices, monitoring cash flow carefully, and regularly evaluating spending, business leaders can operate sustainably without sacrificing growth or quality. These strategies are not temporary workarounds but foundational practices that create stronger, more efficient organizations. Budget constraints, when managed properly, become a competitive advantage that drives innovation and accountability throughout the entire business.

Inside a China Eyewear Factory: How Eyewear Goes from Design and Material Selection to Mass Production

Building Emotional Wellness Through Professional Guidance and Support

How to Choose an Eyewear Manufacturer in China for Your European or American Private Label Brand
Alex Pettyfer Net Worth, Wife, Age, Height, Children, Career and More
Brad Williams Net Worth, Wife, Height, Age, Daughter, Family, Career and More
Eldorado.gg Review 2026: How It Works, Safety, Fees, and Risks
-
Celebrity11 months ago
Alex Pettyfer Net Worth, Wife, Age, Height, Children, Career and More
-
Celebrity11 months ago
Brad Williams Net Worth, Wife, Height, Age, Daughter, Family, Career and More
-
Blog3 months ago
Eldorado.gg Review 2026: How It Works, Safety, Fees, and Risks
-
 Anime12 months ago
Sanzoku Bandits of One Piece: Origins, Higuma, and Their Role in Dawn Island
-
 Celebrity11 months ago
John McGinn Net Worth, Age, Height, Wife, Childrens, Career and More
-
 Celebrity11 months ago
Frances de la Tour Net Worth, Age, Height, Husband, Childrens, Career and More
-
 Anime12 months ago
Shimotsuki Ushimaru – The Last Daimyo of Wano Country Explained
-
 Celebrity12 months ago
Will Trickett Net Worth, Wife, Childrens, Age, Career and More